A two-person consulting firm and a 50-person manufacturing company will get wildly different quotes for the same plan type. The final number depends on coverage tier, plan design, location, group size, carrier, contribution strategy, and how the plan is funded.
According to the 2025 KFF Employer Health Benefits Survey, average annual premiums reached $9,325 for single coverage and $26,993 for family coverage among firms with 10 or more workers. Those numbers are a useful benchmark, not a quote for your business.
This guide separates total premiums from what employers actually pay, breaks down the factors that move pricing, and shows you how to build a realistic benefits budget.
TL;DR
- National averages are benchmarks, not quotes: your cost hinges on group size, location, and plan design.
- True budgets stack premium contributions with admin fees, compliance work, and optional HSA, HRA, or wellness funding.
- Lower premiums often mean higher deductibles or narrower networks, shifting cost to employees.
- Higher employer spend often returns value through stronger recruiting, retention, and access to care.
How Much Does Employer Health Insurance Cost?
Employers need to separate the total plan premium from the amount the employer actually pays. Employees typically cover a share through payroll deductions, so the sticker price on a quote isn't your final bill.
Per KFF's 2025 survey, the average worker contribution was $1,440 per year ($120/month) for single coverage and $6,850 per year ($571/month) for family coverage.
That leaves employers covering roughly 84% of single-coverage premiums and 74% of family premiums on average. The survey covers employers with 10+ workers, so it isn't a direct stand-in for a five-person shop.
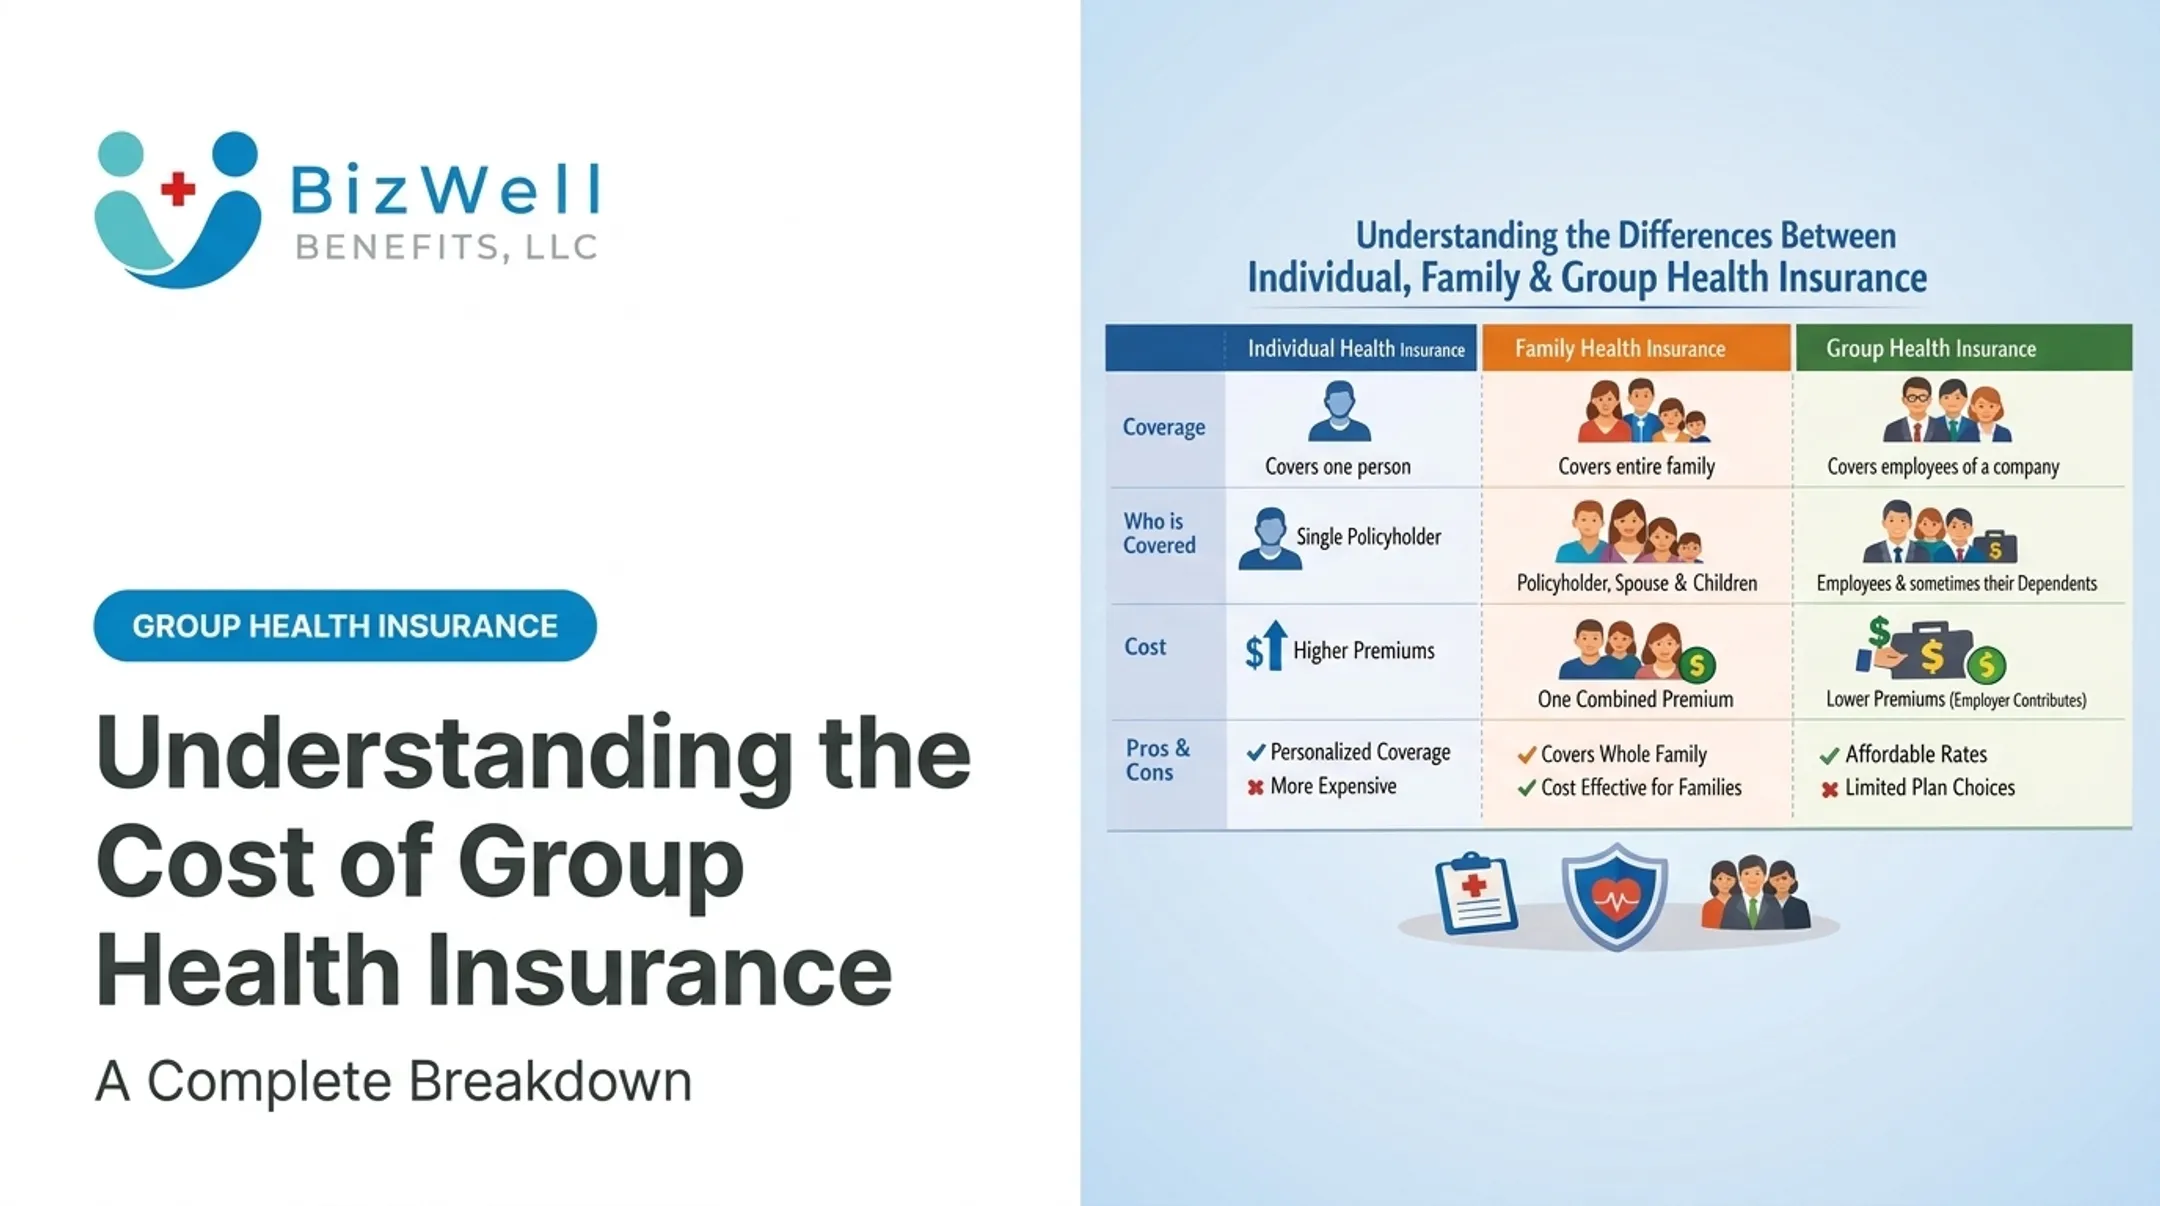
Coverage tiers also change your total spend significantly:
- Employee-only: Lowest cost; covers only the worker
- Employee-plus-spouse: Adds a second adult
- Employee-plus-child(ren): Covers kids without a spouse
- Family coverage: Highest cost; covers the full household
A workforce heavy on family coverage costs more than one dominated by single employees under 30. Enrollment mix matters as much as the plan you select.
Employer Contribution and Employee Contribution
Employers generally structure contributions one of three ways:
- Fixed percentage of employee-only premium — for example, paying 70% or 80% regardless of the specific plan cost
- Flat dollar amount per employee, regardless of the premium
- Tiered contributions, funding a different share for dependent coverage than for the employee alone
Contribution shares vary by business size, industry, and talent strategy. Model your percentage against real quotes rather than a generic benchmark.
To estimate your annual premium expense, multiply the number of enrolled employees in each tier by the monthly premium for that tier, then by your contribution percentage, then by 12.
Example only: 8 employees on employee-only coverage and 4 on family coverage. At a 75% employer share, with monthly premiums of $550 (single) and $1,600 (family), annual employer cost is about $76,320. Use this as math practice, not a benchmark for your shop.
Total Employer Cost Beyond Premiums
Premiums are just one piece. A complete budget also accounts for:
- Administrative and platform fees for enrollment, benefits admin, and payroll coordination (sometimes bundled into carrier pricing)
- Compliance costs for required notices, reporting, and SBC distribution
- Broker or advisory support, often carrier-paid rather than billed to you
- HSA/HRA contributions — for 2026, statutory HSA limits are $4,400 self-only and $8,750 family, per IRS Rev. Proc. 2025-19
- Wellness or telehealth programs
- Stop-loss premiums — relevant for self-funded arrangements protecting against large claims
- Implementation costs during setup or a carrier switch

Fully insured, level-funded, and self-funded plans each expose you to a different mix of predictable premiums, admin costs, claims risk, and stop-loss protection. We'll unpack that trade-off in the next section.
Key Factors That Affect Employer Health Insurance Cost
Pricing reflects two things at once: the expected cost of caring for your specific population, and how the plan itself is designed and administered.
Group Size and Applicable Market
Group size changes both your rating rules and your compliance obligations:
- Small group is generally 1-50 employees under the SHOP Marketplace definition, though many states set it at 2-50
- Large group typically starts at 51+ employees, though some states use 101+
- Applicable Large Employer (ALE) status under the ACA kicks in at 50 full-time-equivalent employees, triggering employer mandate responsibilities
State rules vary. New York, for instance, defines small group as 1-100 employees. Verify current definitions in your state before finalizing a budget. Definitions are a moving target, and they change how carriers underwrite and rate your group.
BizWell Benefits structures group offerings around small businesses with 2-49 employees and medium-to-larger groups at 50-100+ employees, reflecting how carrier options and rating approaches shift at that threshold.
Workforce and Enrollment Profile
Your team's makeup drives pricing more than most employers realize:
- Age distribution (older workforces generally cost more)
- Tobacco use, where permitted in rating
- Employee-only versus dependent enrollment
- Part-time versus full-time eligibility
- Geographic distribution across offices or remote workers
- Overall participation rate
Under CMS market rating rules, small-group age rating is capped at a 3:1 ratio and tobacco rating at 1.5:1. Insurers also can't use individual health status to set eligibility or premiums; that has been prohibited since 2014. Don't treat an employee's medical history as a pricing lever. Regulated small-group markets don't work that way.
Plan Design and Provider Network
Plan type trades monthly premium against flexibility:
| Plan Type | Network Flexibility | Typical Premium |
|---|---|---|
| PPO | Out-of-network allowed, no referrals | Higher |
| HMO | In-network only, referrals required | Lower |
| EPO | In-network only, no referrals | Lower-mid |
| POS | Referral-based, some out-of-network | Mid |
| HDHP | Varies by network | Lowest, higher deductible |
Broad networks cost more but reduce access friction. Narrow or tiered networks lower premiums but can force employees to switch doctors. Before choosing, check whether your employees' actual doctors, hospitals, and prescriptions are in-network, and whether the network holds up if your team travels or works remotely.

Funding Model and Cost-Sharing Strategy
Three funding approaches carry different risk profiles:
- Fully insured: You pay a set premium; the carrier assumes claims risk
- Self-funded: You pay actual claims plus admin costs; risk and potential savings are both higher
- Level-funded: A fixed monthly payment covers estimated claims, admin, and stop-loss, blending predictability with some self-funded upside
Kaiser Family Foundation (KFF) reports that 67% of covered workers were in self-funded plans in 2025, though that share drops to 27% at firms with 10-199 employees versus 80% at larger firms. Self-funding scales with size and risk tolerance.
Raising deductibles or employee contributions lowers your premium expense but has limits. For 2026, the IRS affordability threshold sits at 9.96% of household income, and minimum-value coverage must cover at least 60% of expected costs (IRS guidance). Push cost-sharing too far and you risk both affordability penalties and employee dissatisfaction.
Low-Cost vs. Higher-Cost Plans
A cheaper monthly premium isn't automatically the better deal. Compare plans across:
- Deductible and out-of-pocket maximum
- Provider choice and network breadth
- Prescription formulary coverage
- Realistic employee usage patterns
A plan with a rock-bottom premium but a $7,000 deductible might go unused if employees can't afford to trigger it. Weigh total expected cost, not just the line item on your invoice.
How to Estimate the Right Employer Health Insurance Budget
Skip the national-average shortcut. Start with your own numbers: eligible employees, expected dependents, likely enrollment by tier, and your contribution policy.
Build a worksheet with separate lines for:
- Employer premium contributions
- Employee payroll deductions
- HSA/HRA funding
- Administration and compliance
- Broker or technology support
- A contingency line for renewal increases

On that last point, don't guess. Mercer projected a 6.7% increase in total employer health-benefit costs for 2026. Build a similar trend assumption into renewal planning instead of budgeting flat year over year.
From there, model at least two or three scenarios side by side:
- A richer PPO with lower deductibles
- A structured HMO or EPO with tighter networks
- An HDHP paired with an HSA or employer-funded account
For 2026, qualifying HDHPs need minimum deductibles of $1,700 self-only / $3,400 family, with out-of-pocket maximums capped at $8,500 / $17,000 (IRS Rev. Proc. 2025-19).
Compare employer cost and employee out-of-pocket exposure across all three scenarios before you lock a budget. That comparison only holds if you also account for costs that never show up on the premium line.
What Most Employers Miss
The most common budgeting mistake is planning only for the premium line and ignoring everything downstream:
- Deductibles and out-of-pocket maximums employees will actually hit
- Dependent enrollment shifts mid-year
- Administrative and implementation work
- How renewal increases compound over several years
A lower premium often shifts cost onto employees through higher deductibles, coinsurance, or narrower networks. That trade-off can cut participation and satisfaction even when the invoice looks better on paper.
Before signing anything:
- Request quotes from multiple carriers, not just your incumbent
- Review the Summary of Benefits and Coverage line by line
- Check the provider directory and prescription formulary against your team's actual needs
- Confirm participation rules and renewal terms upfront
An independent broker can make that checklist practical. BizWell Benefits compares carriers and plan designs side by side, explains the trade-offs in plain language, and helps small businesses match coverage to budget and workforce needs without steering you to one carrier.
Conclusion
Employer health insurance cost goes beyond the premium contribution. Total cost includes premiums, admin work, compliance, and often HSA or HRA funding, plus what employees still pay through deductions and out-of-pocket costs.
The right budget doesn't chase the lowest number on a quote. It balances affordability, network access, plan quality, and long-term sustainability. A plan employees can't actually use only defers cost rather than saving money.
If you're comparing group health options for your business, BizWell Benefits offers free, no-pressure consultations to walk through carriers and plan designs that fit your team. Reach Katherine Nguyen at 713-352-7573 or info@bizwellbenefits.com.
Frequently Asked Questions
How much does it cost for an employer to provide health insurance?
Cost depends on coverage tier, enrollment mix, plan design, location, group size, contribution strategy, and funding model. Use current KFF or BLS benchmarks as context, but get a customized quote for real numbers.
Is it better to get health insurance through an employer or buy a private plan?
Employer coverage usually includes a partial premium contribution that private plans lack. Private plans can offer more portability and choice, especially if you qualify for Marketplace subsidies.
Which insurance is best for employees?
It depends on provider needs, prescriptions, expected use, and budget. PPOs cost more for flexibility; HMOs and EPOs cost less with tighter networks; HDHPs with an HSA suit lower-usage employees.
What is a good out-of-pocket maximum?
Balance premium, deductible, and employee wages against the federal limit. For 2026 Marketplace plans, the ceiling is $10,600 individual / $21,200 family. Verify current plan-year limits before you choose.